



WeChat ID :

Login/Register


 Posted on 7 Oct 2026
 5


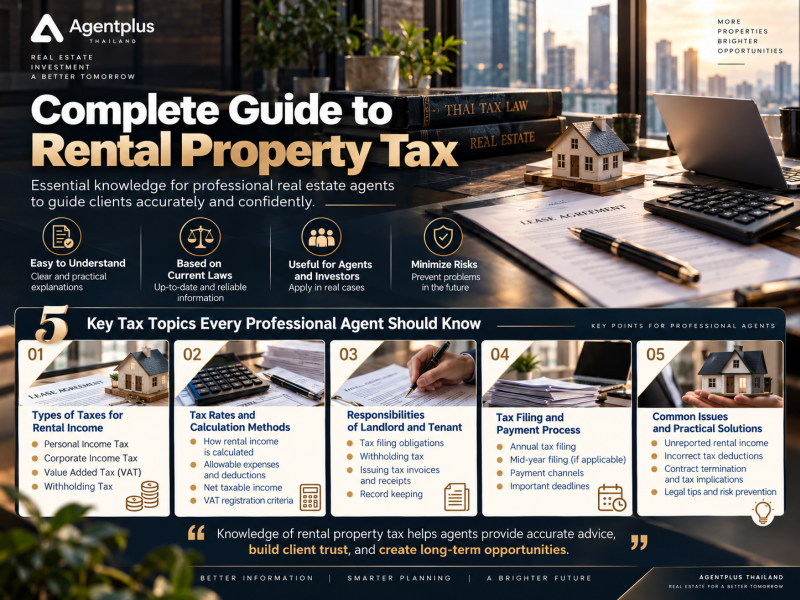
Special Analytical Report: Rental Property Taxation in Thailand — Personal Income Tax, 5% Withholding Tax, VAT Exemptions, and Contract Structuring
Rental property investments across key economic corridors like Bangkok, Pattaya, Chonburi, and the EEC require strict compliance with Thai tax laws. Managing lease transactions involves personal/corporate income tax, withholding tax, and specific exemptions under the Revenue Code.
Personal Income Tax (Section 40(5)): Rental proceeds are classified as Type 5 assessable income. Individuals can deduct actual expenses with proof, or opt for a standard deduction of 30% for buildings/condos and 15% for agricultural land. Long-term advance rental payments can be structured across lease terms using form P.N.D. 93 under statutory guidelines.
5% Withholding Tax: When the lessee is a registered juristic person, they are legally mandated to deduct 5% withholding tax at source. Landlords must declare full gross income on annual returns and use the 5% as a tax credit. For "Net Rent" contracts, the lessee must calculate using the Gross-up formula ($\text{Net Amount} \div 0.95$), absorbing the resulting tax liability.
VAT Exemption (Section 81(1)(tor)): Pure real estate leases (residential, commercial, warehouses) are strictly exempt from 7% VAT. However, related services such as building management, utilities, or maintenance are subject to 7% VAT and must be invoiced separately. The 1.8-million-baht VAT registration threshold applies strictly to taxable service revenue, excluding rental income.
Agentplus (Thailand) Co., Ltd., led by CEO Ms. Patima Jirathamrongchat (MissKann)—a 20-year real estate veteran, TREBS RE131 licensing course lecturer, and recipient of the Living Insider "TOP LUXURY AGENT" award—is Thailand's premier Real Estate Brokerage and Investment Consultancy. Agentplus provides specialized advice on lease structuring, Gross/Net rent modeling, withholding tax documentation, and international tenant placement across Pattaya and the EEC.